


AMD Stock Price Prediction: One Growth Opportunity Could Push Shares Much Higher
AMD Stock Price Prediction: One Growth Opportunity Could Push Shares Much Higher
Vandita JadejaFri, October 23, 2026 at 3:00 PM UTC
0
AMD (AMD)Quick Read -
AMD is rated HOLD at $546 after a 156% YTD rally, with Helios the key swing factor to push shares toward $689.
NVIDIA trades at 44x earnings despite 105% revenue growth, capping the valuation premium AMD can command at 137x trailing earnings.
At 137x trailing earnings, AMD faces supply constraints on HBM and wafers, early Helios yield issues, and an $800M export control charge.
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
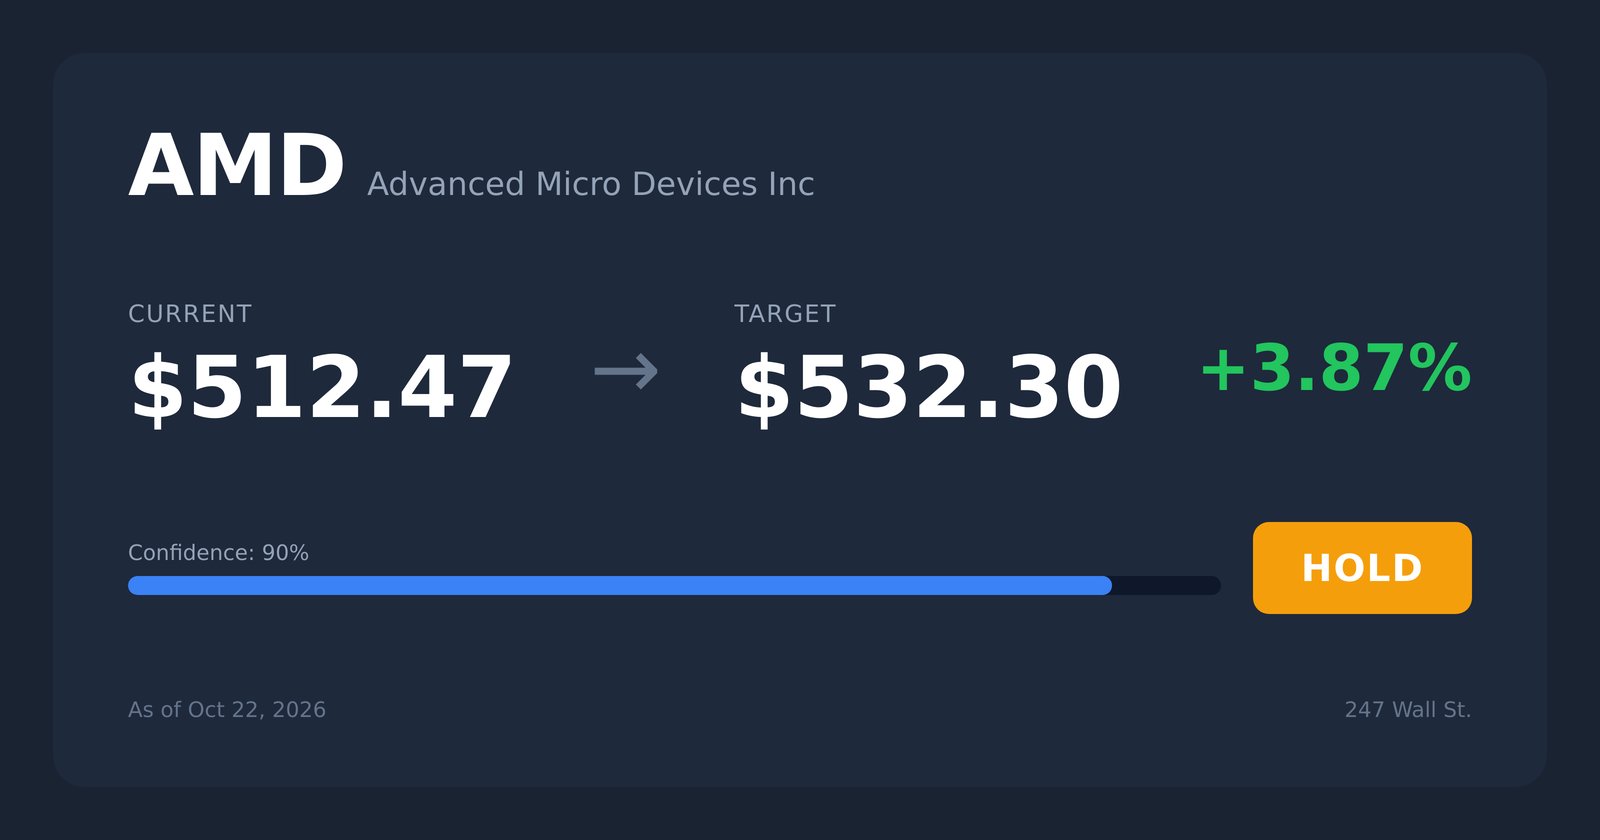
Advanced Micro Devices (NASDAQ:AMD) shares are trading at $549.35 this morning. Our 24/7 Wall St. price target for AMD is $546.06 over the next 12 months. That implies 0.6% downside, so our model rates the stock a hold. Confidence is high, at 90%.
24/7 Wall St. Price Target Summary
Metric
Value
Current Price
$549.35
Price Target from 24/7 Wall St.
$546.06
Upside/Downside
-0.6%
Recommendation
Confidence Level
90%
AMD Price Target — 24/7 Wall St.
The stock is up 156.51% year to date as the AI accelerator story moved from plans to signed contracts. Our model says most of that good news is already in the price.
One growth opportunity, the Helios rack-scale AI ramp, is the swing factor that could push shares well past our target.
Why We Could Be Wrong
The 24/7 Wall St. price target sits just below where AMD trades today. Real upside could come from Helios shipments ramping faster than planned, or from server CPU demand that management says is exceeding supply.
Consider our target one datapoint among many. A detailed bull case appears below.
AMD Price Scenario — 24/7 Wall St.A 9% Pullback Interrupts a 156% Rally
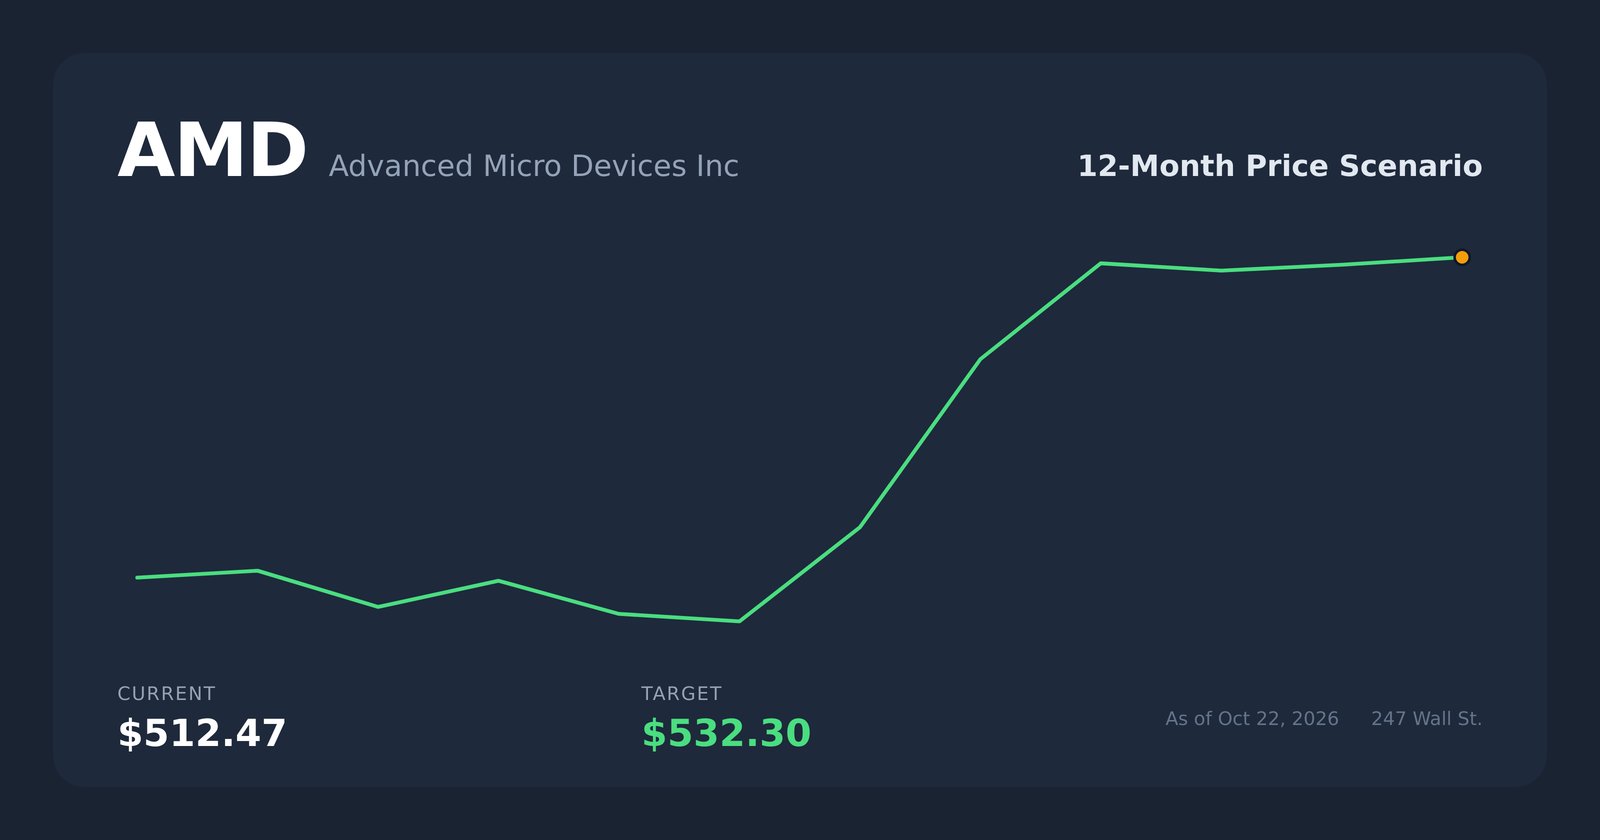
AMD fell 9.28% over the past week and 1.87% over the past month. Shares now sit 16.6% below the 52-week high of $658.52, though still far above the $188.22 low.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
Fundamentals support much of the run. Second-quarter revenue rose 50.1% to $11.54 billion, beating the $11.31 billion consensus, and non-GAAP EPS of $1.66 exceeded the $1.61 estimate. Data Center revenue jumped 107% to $6.72 billion. Third-quarter guidance calls for about $13 billion, plus or minus $300 million.
Helios Could Drive a Run to $689
AMD holds gigawatt-scale commitments from OpenAI (6 gigawatts), Meta Platforms (NASDAQ:META) (up to 6 GW) and Anthropic (up to 2 gigawatts of MI450 GPUs, starting in the first half of 2027). Microsoft (NASDAQ:MSFT) plans Helios at scale on Azure.
CEO Lisa Su said in August that "customer pull for Helios is very strong and tracking ahead of our initial forecast," with revenue per gigawatt in the "double-digit billions."
Advertisement
Management expects Data Center revenue to more than double in 2027 and projects the AI accelerator market reaching about $1.4 trillion by 2030. Analysts agree: 45 rate AMD a buy or strong buy, none rate it a sell, and the consensus target is $627.65. Our bull scenario reaches $689.35.
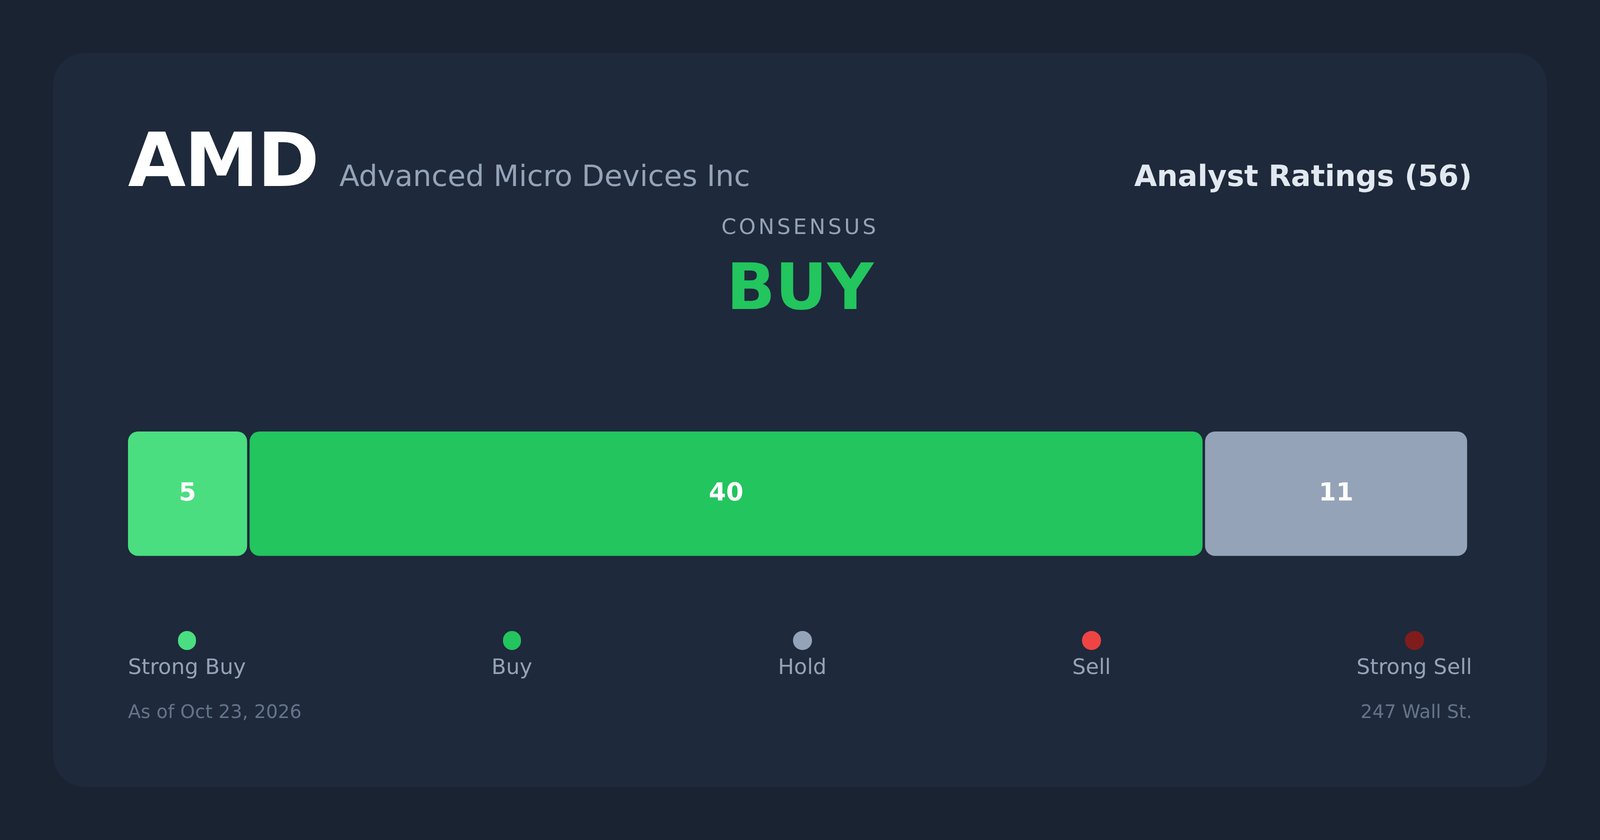
AMD Analyst Ratings — 24/7 Wall St.Valuation Leaves Little Margin for Stumbles
At 137x trailing earnings, AMD needs clean execution. Management noted supply limits on wafers, packaging and HBM, plus early Helios yields. Gaming revenue fell 31%, and Q2 free cash flow slipped 9.89% as capex jumped 186.52%. Export controls already cost an $800M MI308 charge.
Counterpoint: that capex funds the Helios ramp, and the 40x forward P/E looks far more reasonable. Our bear scenario lands at $433.06.
How AMD Compares to NVIDIA and Broadcom
NVIDIA (NASDAQ:NVDA) is AMD's direct AI accelerator rival. Its latest quarterly revenue rose 105.85% to $96.22 billion, yet it trades at just 44x earnings. Faster growth at a lower multiple caps how much premium AMD deserves.
Broadcom (NASDAQ:AVGO) competes for the same hyperscaler budgets with custom accelerators. AI semiconductor revenue grew 221% to $16.7 billion, showing how the market rewards proven AI scale.
Company
Trailing P/E
Latest Quarter Revenue Growth
137x
50.1%
44x
105.85%
Broadcom
n/a
85.5%
Against this group, our target looks reasonable.
Our HOLD Rating Stands, With Helios as the Trigger
The 24/7 Wall St. price target of $546.06 and hold rating carry 90% confidence. Valuation tips the scale.
I would turn more positive if Q3 results confirm the Helios step-up and guidance tops $13 billion. I would stay cautious if supply or yield problems push the ramp further into 2027. Today, AMD is fairly valued.
Year
Price Target (Base) from 24/7 Wall St.
Bull Case
2026
$557.08
$565.62
2027
$546.06
$689.35
2028
$580.42
$768.63
2029
$601.18
$833.38
2030
$606.62
$889.79
The projections rest on AMD continuing to execute on its current AI strategy. A faster MI500 ramp would move results toward the bull column, while tighter export controls or HBM shortages could pull them lower.
The accelerator story also keeps pulling in the companies that power and cool the racks, which is why we put together a report on seven AI infrastructure suppliers that aren't chipmakers.
Released: The Definitive Guide to Retirement Income
(Sponsor) Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out.
It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan. That is exactly what The Definitive Guide to Retirement Income helps answer. It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn more here. Learn More Here ›
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
